The Georgia Appraisal Clause, Explained Sentence by Sentence
Most policyholders never read the appraisal paragraph until they need it. Here’s what each sentence means and where disputes usually start.
Read guide
When your carrier accepts the claim but the check won’t cover the repair, Georgia Insurance Appraiser builds an independent, line-by-line valuation and takes it through the appraisal process written into your policy.
Most underpaid claims aren’t denied — they’re just short. A missing roof slope, a mismatched floor, a code item nobody priced. Georgia Insurance Appraiser exists for that gap between “covered” and “paid in full.”
Eleven services built around one job: producing a valuation of your loss that holds up. Start with an estimate review, or bring us in once appraisal has been demanded.
 Core service
We serve as your appointed appraiser once either side invokes the policy’s appraisal provision.
Most requestedHail-bruised shingles, metal panels and soft metals — repair versus full replacement disputes.
 Storm
Straight-line winds, tornado paths and severe thunderstorm losses, from lifted shingles to structural damage.
 Coastal & inland
Named-storm losses on the coast and inland — wind-driven rain, roof failure and tree impacts.
Single-family, townhome and condo unit claims where the carrier’s estimate leaves out real repair costs.
Retail, office, multifamily, church, warehouse and HOA losses with larger scopes and higher stakes.
Sudden pipe bursts, appliance failures and storm water intrusion — drying, tear-out and rebuild.
Kitchen fires to total losses — structure, smoke and soot cleaning, odor, and contents.
Pines and hardwoods on roofs, decks and vehicles — removal, structural repair and debris limits.
A line-by-line audit of the carrier’s Xactimate or Symbility estimate before you decide on appraisal.
Neutral umpire service for appraisal panels that reach an impasse, plus guidance on umpire selection.
Type in the two numbers you already have. If the difference is large, a conversation with a Georgia Insurance Appraiser makes sense. If it’s small, a documented supplement request may close it faster and cheaper.
The full appraisal value estimator adds appraiser and umpire fees so you can see a realistic net figure.
See all six free toolsThe appraisal clause turns an open-ended argument into a defined process with a binding result. Here is how Georgia Insurance Appraiser takes a file from first call to signed award.
We read your policy, the carrier’s estimate and your photos, then tell you plainly whether appraisal fits your situation.
On-site inspection, measurements and a line-item Xactimate estimate priced for your Georgia ZIP code.
Appraisal is invoked in writing and Georgia Insurance Appraiser is named as your appraiser within the policy deadline.
We work line by line with the carrier’s appraiser. Most disputes narrow sharply at this stage.
Unresolved items go to a neutral umpire. Two signatures set the amount of loss and payment follows.
Ice in Blue Ridge, hail in Marietta, tornadoes in Macon, hurricanes in Valdosta and Brunswick. A Georgia Insurance Appraiser has to know how each region’s weather shows up on a roof — and in an estimate.
Elevation brings winter weather the rest of the state rarely sees. Ice-laden limbs, collapsed gutters and burst pipes in seasonal cabins are the claims we see most in Rabun, Union, Fannin, Gilmer and Whitfield counties.
Communities: Rome, Dalton, Calhoun, Blue Ridge, Ellijay, Dahlonega
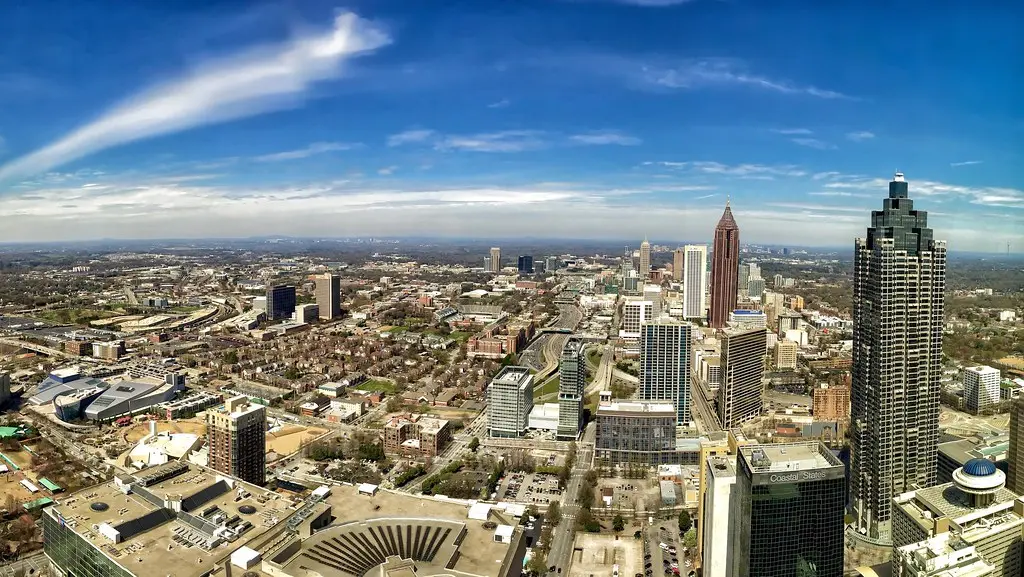
The busiest claim market in the Southeast. Spring hail tracks through Cobb, Cherokee, Gwinnett and North Fulton, while in-town neighborhoods add historic homes and high-rise condos to the mix.
Communities: Atlanta, Marietta, Alpharetta, Sandy Springs, Roswell, Lawrenceville, Decatur
Spring squall lines strengthen across the Piedmont. Mature oaks over historic homes in Macon and Athens mean tree impacts are as common as roof damage.
Communities: Athens, Macon, Columbus, Warner Robins, Milledgeville, LaGrange
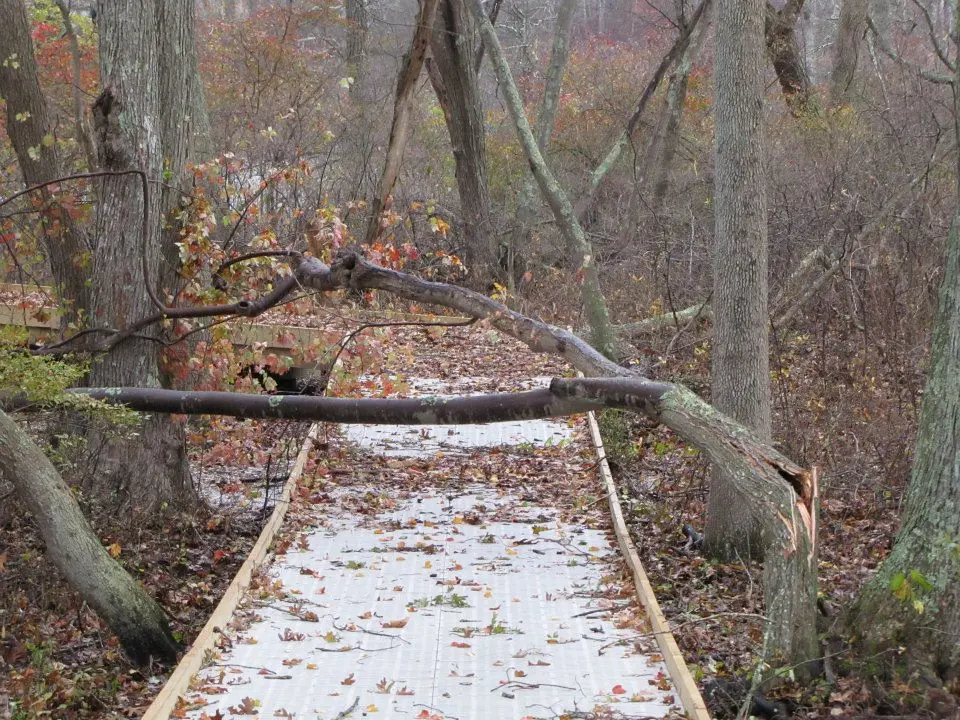
Gulf hurricanes cross this region with surprising strength. Pine forests, pecan orchards and farm outbuildings create claims that blend residential, agricultural and commercial coverage.
Communities: Albany, Valdosta, Tifton, Thomasville, Moultrie, Americus
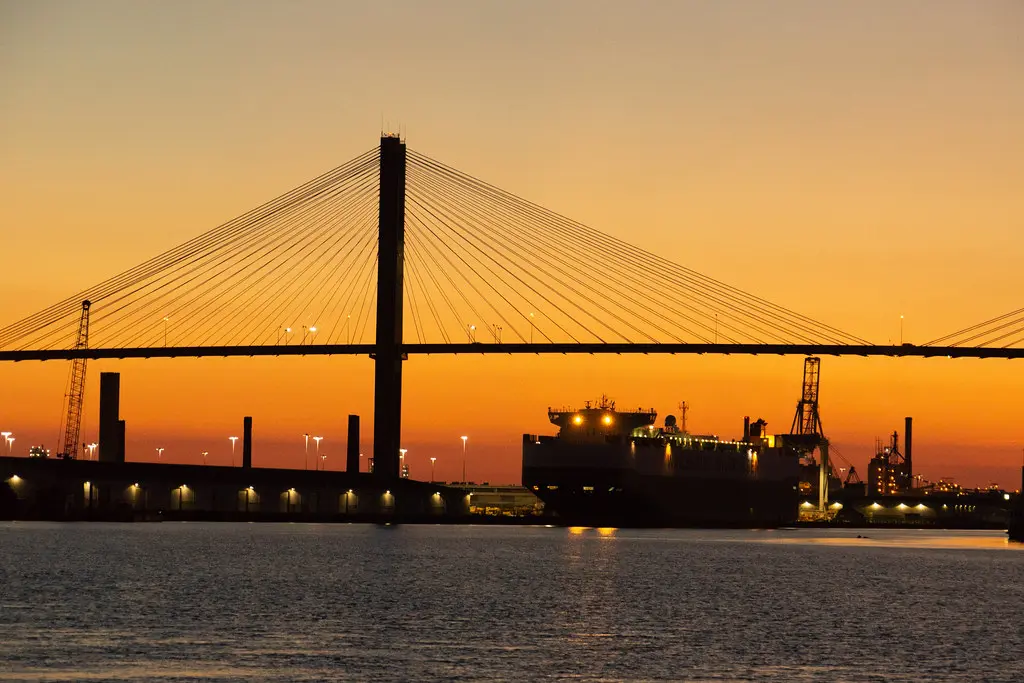
Named-storm deductibles, wind-versus-flood questions and historic buildings define coastal claims from Chatham County to Camden County.
Communities: Savannah, Brunswick, St. Simons Island, Richmond Hill, Kingsland, St. Marys
Run the numbers before you pick up the phone. Every tool works in your browser — nothing is stored or sent.
 CalculatorΔ$
See the disputed amount, a projected award and what you’d net after appraiser and umpire fees.
Open tool CalculatorACV
Estimate the first ACV check, the recoverable depreciation held back and the total once repairs are done.
Open tool Calculator▲
Convert a footprint into true roof squares using pitch and waste — then check the carrier’s numbers.
Open toolCalculator%Turn a percentage wind/hail or named-storm deductible into dollars and see what a claim would actually pay.
Open tool Planner◷
Map notice, proof-of-loss, depreciation and suit-limitation dates from your date of loss — and export them.
Open toolChecklist✓Answer 12 yes/no questions to score your file and get a personal to-do list before invoking appraisal.
Open toolWe serve every county in the state. These are the communities where Georgia Insurance Appraiser handles claims most often.
Each one solves a different problem. Picking the right help first saves time and fees — and Georgia Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
| Question | Georgia Insurance Appraiser | Public adjuster | Attorney |
|---|---|---|---|
| Main job | Value the amount of loss | Manage & negotiate the claim | Legal disputes & litigation |
| Best stage | Coverage accepted, number disputed | Early, from first notice | Denials, bad faith, deadlines |
| Result | Binding award (2 of 3 signatures) | Negotiated settlement | Settlement or judgment |
| Decides coverage? | No | No | Argues it in court |
Straight answers about how appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree a loss is covered but disagree on the cost. As your appointed appraiser we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, if needed, present unresolved items to a neutral umpire.
A public adjuster manages and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate claims outside appraisal and we don’t give legal advice.
When coverage is accepted, you have the carrier’s estimate, and the gap between it and your contractor’s number is meaningful — generally more than about 10% or several thousand dollars.
Yes, on the amount of loss, once any two of the three panel members sign. That’s why documentation matters so much before you invoke appraisal.
Each side pays its own appraiser and usually half of the umpire. We put our fee in writing before any work starts, and our first conversation is free.
Yes. We work statewide across all 159 counties, with regular work in metro Atlanta, Savannah, Augusta, Columbus, Macon, Athens and South Georgia.
Practical guides from the Georgia Insurance Appraiser team on policy language, documentation and strategy.
Most policyholders never read the appraisal paragraph until they need it. Here’s what each sentence means and where disputes usually start.
Read guideThree professionals, three different jobs. Picking the wrong one first can cost you time and money.
Read guideThe photos you take in the first 48 hours after a hail storm often decide the claim. Here’s what to capture, safely.
Read guideA short review now can save you from accepting a settlement that won’t cover the repair.
Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing — no pressure, no obligation.
